



The China Advantage in Silicone: Four Numbers That Explain It
Sourcing Analysis · Anysil Silicone Co., Ltd, Panyu, Guangzhou · 4 min read
Talk about China sourcing gets ideological fast. The reality is simpler and more useful: four structural numbers explain most of the advantage - and two honest caveats explain where it stops.
Meta description: Roughly 77% of global silicone monomer capacity, a cluster that quotes samples in 24 hours, and a third of world textile exports. What China's supply chain advantage actually rests on - and where it stops. Slug: /blog/china-silicone-supply-chain-advantage Tags: China supply chain, silicone sourcing, liquid silicone rubber, silicone ink, Guangzhou manufacturing, Panyu cluster, organosilicon
Buyers comparing China against Vietnam, India, Turkey or Mexico usually end up arguing about labour cost. That is the least interesting variable in silicone. What actually determines your price, lead time and ability to customise is where the raw material comes from and how tightly the supply chain is packed together. On both counts, China's position is structural rather than incidental.
The three numbers up front
~77% - China's share of global organosilicon (silicone) monomer capacity
70-75% - China's share of global silicon metal production, the upstream feedstock
~32% - China's share of global textile and apparel exports, the demand anchor
1. Upstream control: the chain starts here
Silicone begins as silicon metal, becomes siloxane intermediates, and ends as monomer, gum or liquid silicone rubber. China produces roughly 70-75% of the world's silicon metal and holds about 77% of global organosilicon monomer capacity. Global silicone monomer consumption is running near 6.8 million tonnes in 2026, up about 6.5% year on year.
When the feedstock, the intermediate and the finished compound come from the same country - often the same corporate group - there are fewer price layers, shorter inventory buffers and faster response to a specification change. Buyers outside this chain inherit each of those layers as cost and delay.
2. Cluster density: 30 minutes, 24 hours, 48 hours
Guangdong Province's 2026 garment-industry action plan describes its Panyu fast-fashion base in a way that is unusually concrete: supply chain resources matched within 30 minutes, samples confirmed within 24 hours, and complete orders in as little as 48 hours. More than 5,000 garment factories operate within a 50 km² radius of Guangzhou.
This is the advantage that is hardest to copy. Silicon metal and monomer capacity can be built elsewhere with enough capital and electricity. A cluster where fabric mills, silicone suppliers, print shops, tooling, trims and finishing sit within a short drive - and where all of them share the same engineers, the same machinery suppliers and the same troubleshooting culture - takes decades to assemble.
For silicone specifically, it means a printer can test a new ink on real production fabric the same week it is formulated, and a moulder can iterate a tool without waiting on imported tooling or sample material.
3. The demand anchor: a third of world textile exports
China accounts for roughly 32% of global textile and apparel exports. Guangdong alone had nearly 4,300 above-scale textile and garment enterprises in 2025 with revenue of ¥360 billion, and its garment exports grew 10.4% in early 2026 - the fastest among China's top five export provinces.
Scale in the downstream pulls suppliers upstream. It is not a coincidence that the world's deepest range of screen-printing silicone inks - base coatings, glossy, matte, high-density, embossing, heat transfer, anti-slip, conductive - developed here. The applications existed first; the chemistry followed.
4. Export infrastructure, under pressure
Silicone is a mature Chinese export sector - but the trading environment is genuinely shifting. The EU's CBAM transition period reaches its final phase in 2026, adding carbon-footprint accounting to silicon exports; the US maintains a 25% tariff on Chinese silicon products; and buyers continue to diversify. A credible supplier will document all of it rather than pretend the friction is not there.
Where the advantage stops
Cluster ≠ compliance. A dense manufacturing base also contains a long tail of low-end producers. When ISO 10993-1:2025 tightened thresholds, industry reporting indicated roughly 15% of low-end suppliers exited the medical silicone market. The advantage is in the cluster; the capability is per-company.
Speed ≠ process discipline. Fast quotes and samples say nothing about lot traceability, volatility data or material-change notification. Those you have to ask for.
How to capture the advantage
Buy from the cluster, qualify the company. Use geography to build the shortlist; use documentation to cut it to one.
Ask for substance-level data, not just certificates - PFAS and PFHxA positions, D4/D5/D6 content, volatility figures with test conditions stated.
Test the speed claim. Send a real problem and see whether the sample and technical response match the promise.
Confirm they manufacture. In-house formulation is what turns cluster proximity into responsiveness you can use.
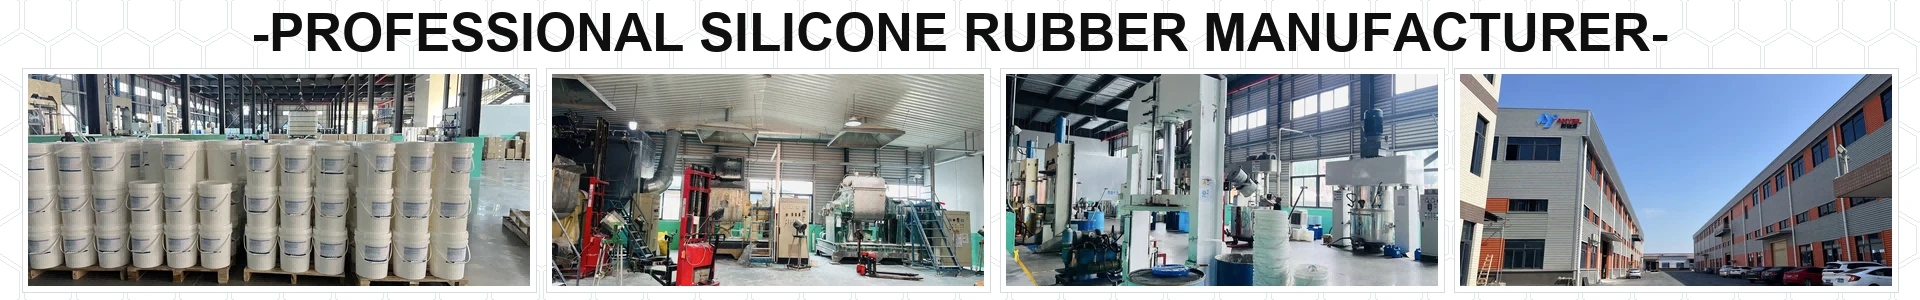
Anysil sits inside this chain: founded 2016 in Panyu District, Guangzhou - the district named in Guangdong's fast-fashion action plan - with R&D, production, sales and technical service under one roof. Everything we sell is made by us, certified to REACH, FDA and LFGB (printing inks additionally RoHS, ISO and OEKO-TEX), and shipped to 50+ countries.
Want to test the cluster advantage?
Send us your substrate, tolerance and compliance requirements. We will come back with a grade recommendation, matched samples and documentation - and run the trial with you before you commit to volume.
Start a technical conversation: https://www.anysil.com/index.php/contact-us-3/
Sources: industry analyses of silicon-based materials and organosilicon monomer capacity, 2026 (China 77% of global monomer capacity; silicon metal 70-75%); global silicone monomer consumption ~6.8 Mt, +6.5% YoY; Guangdong Provincial Action Plan for High-Quality Development of the Garment Industry 2026-2028, as reported September 2026 (Panyu 30-minute resource matching, 24-hour sample confirmation, 48-hour order completion); Guangdong 2025 textile and garment enterprise and revenue figures; China Customs and industry trade statistics on textile and apparel export share (32%) and Guangdong export growth; EU CBAM transition timeline 2026; industry reporting on the exit of ~15% of low-end medical silicone suppliers after ISO 10993-1:2025.
*Anysil Silicone Co., Ltd · No.713 #01 Shiqing Road, Panyu District, Guangzhou, China · Founded 2016 · Exporting to 50+ countries.